New Delhi/Washington DC; September 2026: The United States House of Representatives approved a critical procedural resolution (214-211 vote) to advance the Lindsey O Graham Sanctioning Russia and Iran Act of 2026, paving the way for a final vote. The legislation mandates secondary tariffs of up to 100% on goods imported from the world’s top 05 buyers of Russian crude oil, a list that directly includes India.
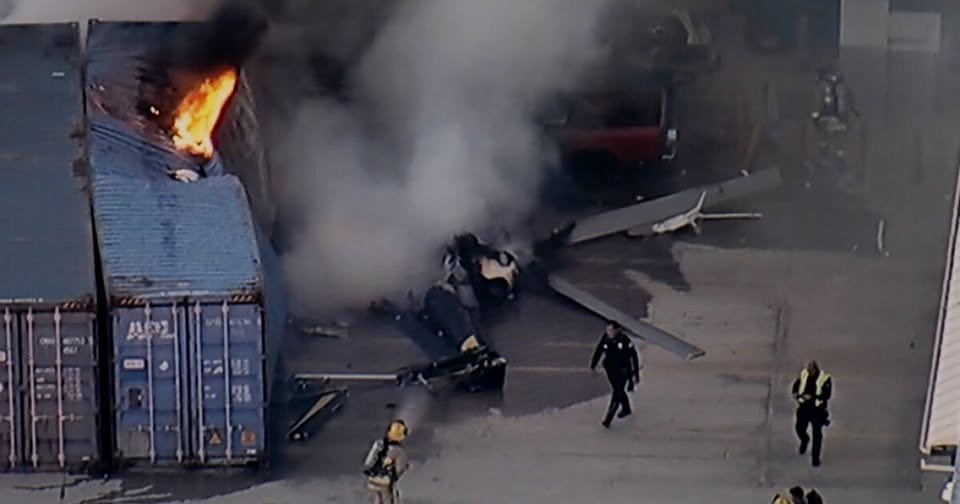
Simultaneously, energy supply chains are recovering from a severe physical shock following the precautionary shutdown of Saudi Arabia's vital 1,200-kilometre East-West Crude Oil Pipeline on September 11, last week. The facility was forced offline after coordinated drone strikes hit key pumping stations in the Riyadh and Medina regions.
Together, these developments place New Delhi at a crossroad, balancing cheap Russian oil imports against existential tariff risks to its massive trade surplus with the United States, all while navigating global crude price spikes. The legislation advancing through the US Congress represents one of the most aggressive secondary sanction efforts targeted at Russian energy buyers to date. Having passed the US Senate on August 07th, by an overwhelming 86-11 margin, the bill moved through the House Rules Committee and cleared a key procedural hurdle in the House early today morning.
The Key Statutory Provisions of the bill include:
Section 113 mandatory ad valorem duties: Directs the Executive Branch, through the United States Trade Representative (USTR), to impose additional ad valorem trade duties of up to 100 per cent on all goods originating from foreign nations identified as top volume purchasers of Russian crude oil or natural gas.
The top-five volume trigger: Section 113(c) explicitly defines covered nations as those that knowingly make new purchases of Russian crude oil or gas and rank among the five largest global importers by total volume. Because India and China consistently top the list of seaborne Russian crude buyers, India falls automatically under this statutory trigger.
Stacking tariffs: Section 113(f) mandates that these 100 per cent secondary duties will be applied in addition to any baseline tariffs, anti-dumping duties, or import charges already active under US law.
Discretionary rate adjustments: Section 113(b) grants statutory power to the USTR to adjust duty rates between 0% and 100% depending on whether a targeted nation takes "significant steps" to systematically reduce or eliminate its Russian energy imports.
Executive waiver authority: Section 115(a) reserves executive waiver authority, allowing the US president to waive or delay tariff enforcement on national security grounds or through formal diplomatic determinations submitted to Congress.
Targeting maritime networks and banking: Beyond import tariffs, the legislation institutes blocking sanctions and port entry bans against the "shadow fleet" of uninsured tankers facilitating Russian oil transport, alongside strict secondary sanctions on Russian financial institutions like Sberbank, VTB Bank, and Gazprom Bank.
The Saudi East-West Pipeline Tragedy –
The physical crisis began on September 10, when multiple suicide drone strikes, those which were launched from Iraqi territory by Iran-backed militia groups had struck critical pumping stations along Saudi Arabia’s East-West Pipeline (Petroline) in the central Riyadh and Medina provinces. Saudi Arabia’s Ministry of Energy officially announced the complete precautionary shutdown of the 1,200-kilometre pipeline network the next day.
Intelligence and satellite assessments confirm structural damage to key pumping infrastructure, with regional officials stating that the pipeline will remain largely out of commission for several weeks while specialised technical teams carry out emergency repairs.
The East-West Pipeline is Saudi Arabia's primary infrastructure safeguard against maritime chokepoint disruptions. Capable of pumping up to 5 to 7 million barrels per day (bpd) from eastern oilfields near Ras Tanura across the Arabian Peninsula to the Red Sea port terminal of Yanbu, the pipeline allows Saudi Aramco to bypass the volatile Strait of Hormuz.
The attack halted the flow of roughly 4 million bpd of crude intended for Red Sea loading. With oil loadings at Yanbu fully suspended and local storage capacity (35 million barrels) estimated to run dry within 5 to 7 days, global crude buyers faced an immediate deficit. Coupled with simultaneous fighting and territorial gains by Houthi forces near the Bab el-Mandeb Strait in the southern Red Sea, Saudi Arabia's dual export corridors have suffered simultaneous compression.
In response, international crude benchmark Brent soared past $108 to $110 per barrel, marking its highest settlement since mid-2024 and triggering widespread inflationary concerns across major Asian import centres.
India’s Dependency on the Saudi East-West Pipeline –
Indian refiners are not directly dependent on the East-West Pipeline for their baseline crude imports. But while India's structural exposure to this specific pipeline is limited, its indirect exposure to the resulting market squeeze is severe. The vast majority of Saudi Arabian crude shipped to India originates from eastern export terminals on the Persian Gulf — principally Ras Tanura and Ju'aymah.
Tankers departing these eastern terminals transit directly across the Arabian Sea to India's west coast refinery hubs at Jamnagar, Vadinar, Mumbai, and Mangalore without using the East-West Pipeline or touching the Red Sea.
Crude flowing through the East-West Pipeline to Yanbu on the Red Sea is primarily allocated to European buyers, US East Coast refineries, and select spot-market tenders.
While Indian refiners occasionally purchase Yanbu cargoes when arbitrage conditions permit, Red Sea loadings represent less than 5 per cent to 8 per cent of India's total Saudi crude intake under standard long-term contracts.
Unless the Persian Gulf and the Strait of Hormuz are completely blocked by hostile naval action, India does not rely on Yanbu or the East-West Pipeline to receive its contracted Saudi Arabian crude.
While direct physical supply chains from Ras Tanura remain operational, the shut-in of 4 million bpd at Yanbu impacts India through three collateral channels:
Western refiners denied Red Sea cargoes are now forced to bid aggressively for Persian Gulf and West African crudes, driving up official selling prices (OSPs) and spot premiums for all Asian buyers.
Escalating drone risks and naval warfare across the Arabian Peninsula have driven marine war-risk insurance premiums up by over 300 per cent for tankers operating in adjacent waters.
Higher crude procurement costs directly erode gross refining margins (GRMs) for both state-owned refiners namely IOCL, BPCL, HPCL, and private operators like Reliance Industries, Nayara Energy.
It’s Impact on the Indian economy –
The simultaneous arrival of a 100% US secondary tariff threat and $100+ global crude oil creates a hard balancing calculus for New Delhi. Since 2022, discounted Russian seaborne crude (Urals and Sokol) has grown to account for 35% to 40% of India’s total daily crude imports (~1.5 to 1.8 million bpd). This discounted supply saved India an estimated $5 billion to $7 billion annually in foreign exchange while keeping domestic petrol and diesel prices stable despite broader global volatility.
If the US sanction bill passes its final House vote and receives presidential signature, India will face a stark choice:
Option A: Maintain Russian import volumes, thereby exposing India’s $80+ billion annual merchandise export trade with the United States to crippling 100 per cent tariffs.
Key Indian sectors, including information technology, pharmaceuticals, textiles, gems and jewellery, automotive components, and engineered goods could lose competitiveness in their largest export market.
Option B: Reduce or cease Russian import volumes, by complying with US statutory thresholds by shifting procurement toward West Asian, African, or American suppliers.
However, replacing 1.6 million bpd of Russian crude during a period when Saudi Arabia's East-West pipeline is down, the Strait of Hormuz being still volatile on its best day, and Brent crude is hovering above $108 per barrel would instantly inflate India’s national import bill, expand its current account deficit (CAD), and exert downward pressure on the Indian Rupee.
The Macroeconomic pressures for India include:
· Every $10 sustained increase in global crude oil prices typically adds 40 to 50 basis points to India’s retail inflation (CPI) and expands its annual current account deficit by approximately $13 billion to $15 billion.
· With state-owned oil marketing companies (OMCs) keeping retail fuel prices regulated to protect consumers, rising landed crude costs threaten to re-introduce under-recoveries, weakening OMC balance sheets.
· A 100% US import tariff would instantly render Indian goods commercially unviable in North America, triggering manufacturing layoffs in export-heavy clusters across Gujarat, Tamil Nadu, Maharashtra, and Punjab.
Options For India –
· India’s primary focus to navigate this situation centres on Section 115(a) executive waiver provisions and USTR discretionary adjustments within the US legislation.
· High-level diplomatic discussions in Washington aim to highlight that Indian purchases of Russian crude serve a stabilising role in global energy markets.
· By refining Russian crude into refined products for global supply, India prevents world oil prices from surging to $150+ per barrel, which would harm Western economies.
· India will likely seek specific national security waivers or extended transition timelines from the White House.
· To lower its volume exposure under Section 113(c), India can incrementally recalibrate its crude basket by expanding term intake from Abu Dhabi (ADNOC), Kuwait (KPC), and Iraq (SOMO), provided Persian Gulf sea lanes remain open.
· Increasing spot buys of US West Texas Intermediate (WTI), West African (Nigerian/Angolan), and Brazilian crudes can also serve to demonstrate a good-faith shift away from Russian dependence.
· Meanwhile, India maintains Strategic Petroleum Reserves with a capacity of 5.33 million metric tons (MMT) stored in underground rock caverns at Visakhapatnam, Mangalore, and Padur, capable of meeting roughly 9.5 days of national crude demand.
· Combined with commercial storage at refineries and pipelines, India holds roughly 65 to 70 days of total oil stock buffer, offering short-term protection against sudden physical shortfalls.
Team Maverick.